How much did Meta raise in 17 days, and what for?
Between Oct. 26 and Nov. 12, Meta sold stock, preferred stock and notes in two currencies. The filings give one purpose: general corporate purposes.
The total came to $25.0 billion of stock, $12.5 billion of preferred stock, $15.0 billion of dollar notes and €9.0 billion of euro notes.
The stock came first. Meta's pricing term sheet shows 40 million Class A shares at $625 and 250 million depositary shares at $50. Those tie to a 6.50% mandatory convertible preferred, which is a preferred share that turns into common stock in August 2029. The stock runs through forward sale agreements, so the cash is expected to arrive on or before Nov. 19, 2027. Our earlier Take on the stock sale has the details.
Then came debt. On Nov. 3 Meta priced $15.0 billion of dollar notes in five pieces running from 2031 to 2056. The 2056 notes pay 7.5%. A day later it priced €9.0 billion of euro notes in six pieces. The longest runs to 2065 at 6.4%.
Here is what that costs. This is our arithmetic from the coupons, not a figure Meta reported. The dollar notes carry about $990 million of interest a year. The preferred pays about $812.5 million a year in dividends. The euro notes add about €479 million. That is roughly $1.8 billion plus €479 million of new yearly payments before any principal comes back.
New yearly payments on Meta's dollar notes and preferred
About $1.8 billion
a year, plus about €479 million on the euro notes
Our arithmetic: $990 million of interest on $15.0 billion of notes plus $812.5 million of preferred dividends.
Meta held $82.4 billion in cash and securities on Sept. 30, according to its prospectus supplement. Its launch release guides to $135 billion to $145 billion of capital spending this year. The filings do not say why Meta wants more money on top of that cash. The size of the spending plan is the likely reason, and that part is our inference.
What makes Equinix's €2.5 billion different?
Equinix promised to match its note proceeds to eligible green projects. Meta made no such promise about its money.
A subsidiary, Equinix Europe 2 Financing Corporation LLC, issued four euro notes on Nov. 9, and Equinix, Inc. guarantees them. The 8-K lists coupons from 4.15% to 5.45% and maturities from 2028 to 2038. Our arithmetic puts the interest at about €121.5 million a year.
The prospectus says Equinix will allocate an amount equal to the net proceeds to "finance or refinance" eligible green projects under its Green Finance Framework. The list covers data center construction (new builds in Europe and North America need a power efficiency ratio of 1.30 or better), renewable energy purchases and efficient cooling. The spending window runs from two years before the sale to three years after. So the notes can reimburse money already spent. Until Equinix assigns the money, it may hold cash or repay existing borrowings.
Equinix is a landlord, and its tenants pay rent after the space is built. Its third-quarter release reports $2.571 billion of revenue and record annualized bookings of $533 million. It expects $5 billion to $6 billion of capital spending in 2026 and nearly 40% more cabinets delivered than first planned. That is a much more specific link between borrowing and building than Meta shows.
Both companies borrowed euros the same week. Meta's 2038 notes carry a 5.400% coupon. Equinix's 2038 notes carry 5.450%. A coupon is not a yield. Equinix sold its notes at 99.552 and we do not have Meta's price, so treat the gap as a rough read. Even so, a data center landlord paid about what Meta did for the same maturity.
What are equity units, and what is Southern Company selling?
Southern is selling a bundle: notes that pay interest now and a purchase contract that settles on Dec. 15, 2029.
Under the usual terms of equity units, settlement is when buyers take Southern shares.
The term sheet shows 35 million units at $50, or $1.75 billion, with room to grow to $2.0 billion. Each unit pays 5.50% on the notes plus 3.125% on the contract, for 8.625% a year in total. On the base deal that is about $151 million a year, by our math. Part of that rate pays for the share option, so it is not comparable to Meta's bond coupons.
The money goes first to older debt. About $135.3 million repurchases about $125.8 million of 4.50% convertible notes due 2027. The rest repays short-term debt, which stood at $776 million on Nov. 11, and covers general corporate purposes. That is in the preliminary prospectus.
Data centers appear only as a risk. The filing cites "projected significant growth in electricity demand driven primarily by data centers and other large load customers." It adds that this creates "capital access and revenue recovery risks" for the electric operating companies. The documents we checked do not tie the units to a signed data center contract. Southern's third-quarter release shows interest expense rose to $842 million from $755 million a year earlier.
The Nexairi Dispatch
See what was promised, and what shows up.
A five-minute weekly email: the companies, money and equipment behind the AI buildout, and the evidence that it became real.
Free · Weekly · Unsubscribe anytime
Who pays after the money is spent?
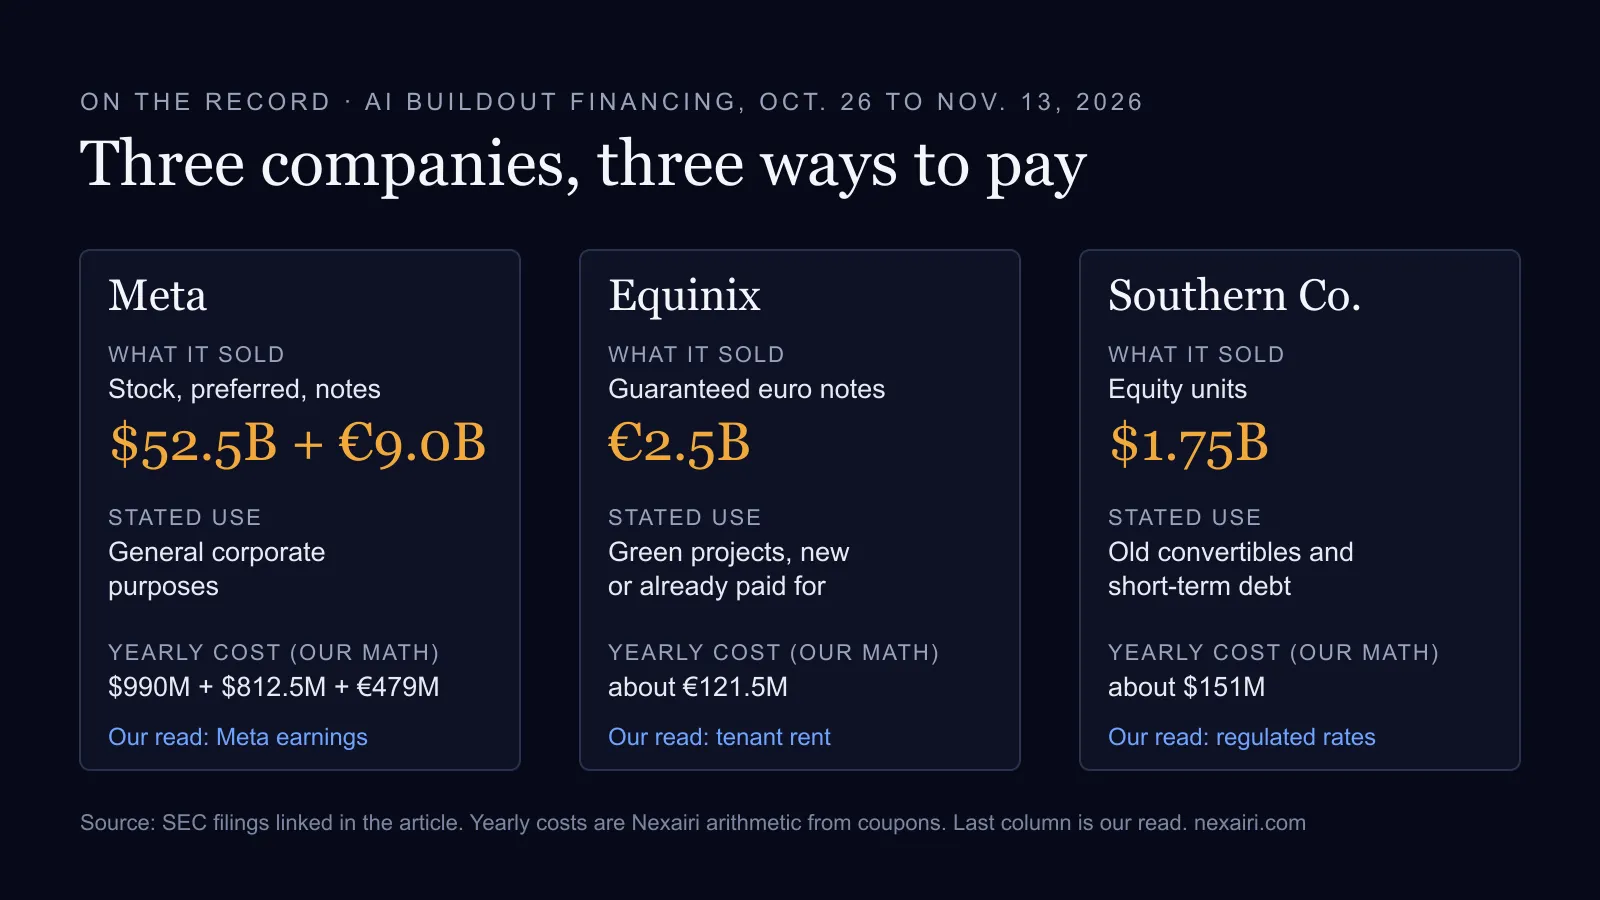
Each raise answers that question differently, and the answer explains the structure. Here are the three side by side.
| Company | What it sold | Stated use | Yearly cost (our math) | Who pays it back (our read) |
|---|---|---|---|---|
| Meta | Stock, preferred, dollar and euro notes | General corporate purposes | $990M interest, $812.5M dividends, €479M interest | Meta's own future earnings |
| Equinix | €2.5B of guaranteed euro notes | Green projects, new or already paid for | About €121.5M interest | Tenants who lease the space |
| Southern | $1.75B of equity units | Old convertible notes, short-term debt | About $151M | Customers, through rates regulators approve |
Our read: paid before, during or after
Meta pays before it earns. It is building capacity for AI products whose revenue it has not yet shown in these filings, so investors carry the risk through stock and long bonds. Equinix gets paid as it delivers, so it can promise investors a narrower use. Southern is paid through regulated rates, and its own filing flags "revenue recovery risks." Regulators decide how much of the new cost customers cover. That last link is the one most likely to be tested.
If one of them is your customer, what do the filings tell you?
They tell you how the customer plans to cover its bills, and whether that plan names your kind of work. Ask three things of any customer or partner.
First, what stage is the money in? Meta's stock cash is not in hand until the forward sales settle. Second, did the filing name a use? Meta's did not, Equinix's did and Southern's named old debt. Third, who ultimately pays? That could be the company's earnings, its tenants or its regulated customers. A supplier to Equinix and a supplier to Meta face different risks even though both sell into the same buildout.
These filings do not show that any of the three will miss a payment. They show where a late or reduced payment would come from.
What has to happen before any of this produces something?
Each company has a date that can settle the question. We track all three on the Meta, Equinix and Southern pages of On the Record.
For Meta, the stock cash arrives by Nov. 19, 2027. Its founder agreement 8-K expects a new non-voting Class C share on Jan. 19, 2027. Meta has said it plans a roughly $60 billion at-the-market stock program once Class C trades, with no agreement signed yet. For Equinix, the test is whether the 2026 delivery and spending numbers hold when it reports the fourth quarter. For Southern, the settlement date is Dec. 15, 2029, and the nearer test is whether its interest expense keeps climbing.
None of these filings shows a finished data center or a powered customer. They show how three companies chose to carry the bill. If you are owed money by one of them, the plain question is who pays the interest in the year the building is still empty. We will check these dates on On the Record as they arrive.
Sources
- Meta pricing term sheet, stock and mandatory convertible preferred (Oct. 26, 2026)
- Meta launch release (Oct. 26, 2026)
- Meta pricing term sheet, dollar notes (Nov. 3, 2026)
- Meta pricing term sheet, euro notes (Nov. 4, 2026)
- Meta 8-K, euro note closing (Nov. 12, 2026)
- Meta prospectus supplement, cash and use of proceeds
- Meta 8-K, founder alignment agreement (Oct. 21, 2026)
- Equinix 8-K, euro notes issued (Nov. 9, 2026)
- Equinix prospectus supplement, green use of proceeds
- Equinix third-quarter 2026 results
- Southern Company equity units term sheet (Nov. 13, 2026)
- Southern Company preliminary prospectus supplement (Nov. 12, 2026)
- Southern Company third-quarter 2026 earnings release
Related Articles on Nexairi